For many individuals and small businesses, accessing formal credit can depend on more than the ability and willingness to repay. A limited financial history, lack of conventional collateral or incomplete information can make it difficult for lenders to assess creditworthiness and for potential borrowers to demonstrate their ability to manage credit.
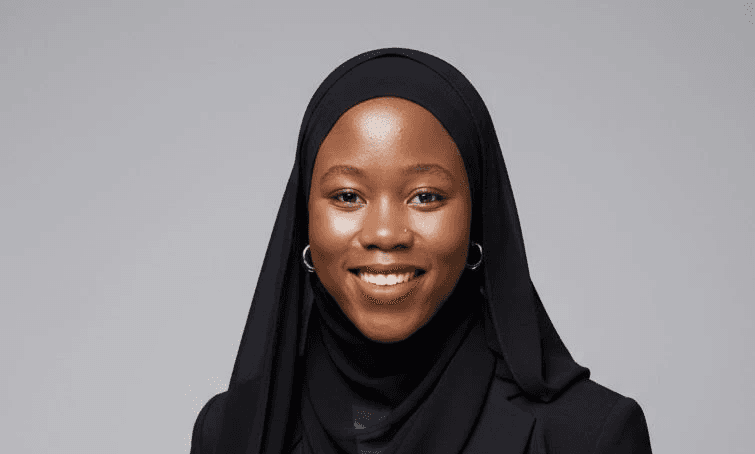
For Sumayyah Nakimuli Sengendo, Managing Director at gnuGrid CRB, better use of credit information and data could help change this reality.
Her journey into fintech began in the capital markets, where she worked as an Equity Trader Intern at African Alliance before moving to Bid Capital as an Investment Analyst. These early experiences gave her an understanding of how financial markets operate, how investors assess risk and the importance of reliable information in making decisions about capital.
Her move to gnuGrid CRB brought these experiences together in a different part of the financial ecosystem.
“Today, as Managing Director of gnuGrid CRB, I have the privilege of leading a business that sits at the intersection of finance, technology and data,” she says.
For her, the connection between these three areas presents an opportunity to address one of the fundamental challenges in financial services: making better decisions with better information.
The Power of Credit Information

Credit information, she believes, is one of the foundations of a strong financial ecosystem.
Lending is ultimately about making decisions under uncertainty. Financial institutions need to understand a customer's existing obligations, repayment behaviour and ability to take on additional credit. When accurate and timely information is available, lenders can make better-informed decisions and manage risk more effectively.
But the value of credit information extends beyond the lender. It can also help individuals and businesses build a financial identity.
In Uganda, where many people and businesses have historically faced barriers to formal finance because they lack sufficient collateral or a long banking history, the ability to demonstrate responsible financial behaviour can be particularly important.
“Better credit information allows us to look beyond what someone owns and increasingly consider how they have behaved financially,” she says.
This shift could have significant implications for financial inclusion. Rather than relying solely on traditional measures of creditworthiness, lenders can increasingly use reliable information to develop a more complete understanding of a customer's financial position.
Better information can also contribute to stability across the financial system by reducing information asymmetry, helping lenders identify existing obligations and supporting more responsible lending decisions.
From Access to Meaningful Inclusion
For underserved individuals and small businesses, the challenge is often not a lack of willingness or ability to repay. It is the absence of sufficient information to demonstrate their creditworthiness.
This is where the growing availability of digital and alternative data could play a role.
According to Sumayyah, customers with limited traditional credit histories may still generate valuable financial signals through their digital and economic activities. When used responsibly, such information can complement traditional credit data and provide lenders with a more complete picture of a customer.
At gnuGrid CRB, this is part of the opportunity she sees in building the information infrastructure needed to support the next phase of Uganda's financial ecosystem. The goal is not simply to make credit decisions faster, but to make them more informed and responsible.
“Ultimately, good credit data can turn financial behaviour into a form of financial identity, and that can open doors for individuals and businesses that may previously have been excluded from formal finance,” she says.
The Challenge Ahead
Despite Uganda's progress in expanding digital financial services, Sumayyah believes the next phase of financial inclusion will require the ecosystem to focus more deeply on the availability and effective use of reliable data.
Financial inclusion, in her view, should not simply mean putting more people on digital wallets or giving them access to financial products. It should mean ensuring that individuals and businesses can access the right financial products, at affordable prices and on the basis of reliable information.
This is particularly important for micro, small and medium enterprises (MSMEs) and individuals operating in the informal economy, many of whom have limited formal credit histories.
Without sufficient information, lenders may exclude potentially creditworthy borrowers or price loans higher because of the uncertainty involved in assessing risk.
The opportunity, therefore, lies in building an ecosystem where quality data can flow responsibly between consumers, businesses, fintechs and financial institutions.
“If we can build an ecosystem where quality data flows responsibly between consumers, businesses, fintechs and financial institutions, I believe Uganda can move beyond simply increasing financial access to creating meaningful, responsible and sustainable financial inclusion,” she says.
Looking Five Years Ahead
Looking to the next five years, Sumayyah envisions a financial ecosystem where inclusion is driven not only by access, but by intelligence, trust and meaningful participation.
She hopes to see a future where a small business owner in the informal sector, a young entrepreneur, a farmer or an individual with limited traditional credit history is not automatically excluded from finance simply because they lack conventional collateral.
Responsible use of alternative data, stronger credit information sharing and digital technologies, she believes, can enable financial institutions to understand customers better and price risk more accurately.
Through her work at gnuGrid CRB, she hopes to contribute to making reliable credit information more accessible, particularly for underserved segments of the market, while supporting financial institutions to make better and more responsible credit decisions.
Her ambition extends beyond making financial services more digital.
“Five years from now, I would be proud if we could look back and say that technology and better use of data did not simply make financial services more digital in Uganda, it made them more inclusive, more transparent, more affordable and more responsible.”
A Message to the Next Generation
For young Ugandans looking to build careers in fintech, her advice begins with curiosity and continuous learning.
The industry is evolving rapidly, requiring professionals to develop an understanding of data, emerging technologies, regulation and business. But technical competence alone is not enough.
When working with financial data, professionals are dealing with information that can influence people's livelihoods, businesses and financial futures. Integrity, confidentiality and sound decision-making are therefore fundamental.
“Competence may open the door, but integrity determines how far you go,” she says.
She also encourages young professionals to build relationships, seek mentors and remain willing to challenge the status quo. Fintech sits at the intersection of finance, technology, regulation and entrepreneurship, making collaboration and continuous learning essential to building a successful career.
The Future of Fintech
As Uganda's fintech ecosystem continues to evolve, Sumayyah believes its future will ultimately depend on more than technological innovation. It will depend on whether that innovation is supported by trusted data, strong partnerships and a commitment to making financial services work better for the people and businesses they serve.
“The future of fintech in Uganda will depend on innovation, trusted data, strong partnerships and our ability to create solutions that make financial services more accessible, affordable and inclusive.”
For a sector increasingly shaped by technology and data, the opportunity ahead may therefore be as much about building trust and financial identity as it is about building new digital products.
For Uganda's fintech ecosystem, better information could be one of the foundations on which a more inclusive and responsible financial future is built.